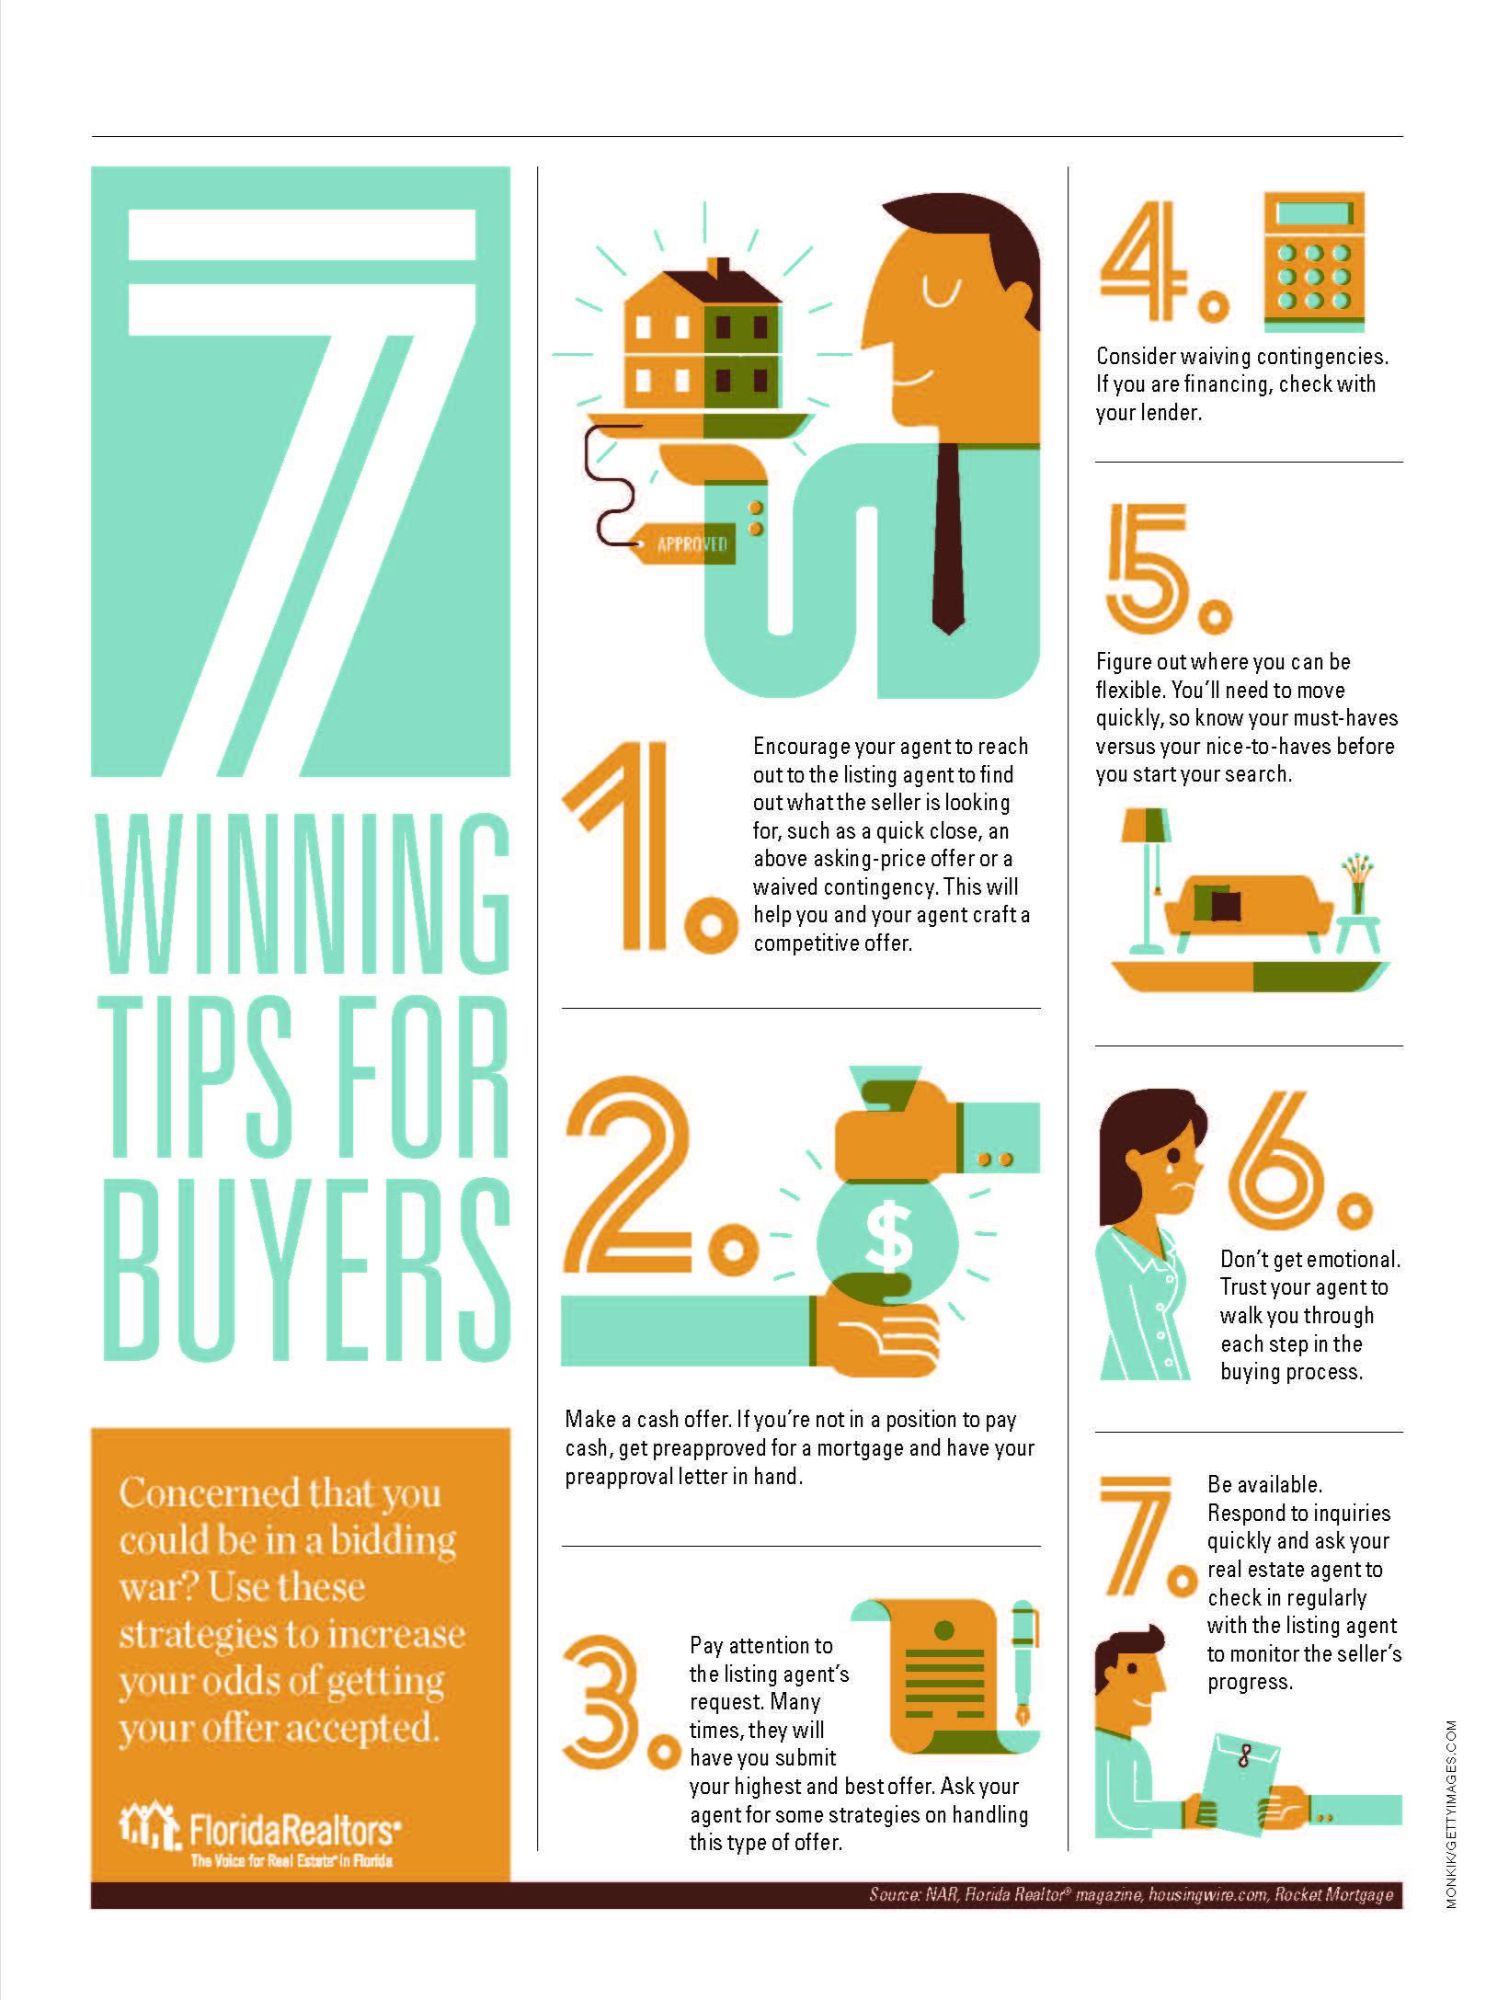
Buying a home is one of the biggest financial decisions you'll make, and when multiple buyers are competing for the same property, it's easy to feel pressured to offer more than you originally planned.
In Southern Maryland, buyers searching in St. Mary's, Charles, and Calvert counties may encounter different levels of competition depending on the neighborhood, price range, property condition, and available inventory. A home in Leonardtown may attract a different buyer pool than one in Waldorf, Prince Frederick, or Lexington Park.
But here's something every buyer should remember: Winning a bidding war doesn't automatically mean you've made a good financial decision.
Knowing how to avoid overpaying for a house means understanding the property's value, establishing a realistic budget, and recognizing when an offer no longer makes financial sense.
Whether you're purchasing your first home, relocating to Southern Maryland, or looking for more space, these strategies can help you compete confidently without putting your long-term financial goals at risk.
1. Understand What a Home Is Really Worth
Before making an offer, it's important to understand the difference between a home's asking price and its likely market value.
A listing price is what the seller is asking. It isn't necessarily what the property is worth or what a lender's appraisal will support.
Review Recently Sold Comparable Homes
One of the most useful tools for evaluating a home's price is a comparative market analysis, commonly called a CMA.
A real estate professional can review recently sold properties that share important characteristics with the home you're considering.
Relevant factors include:
- Location and neighborhood
- Finished living area
- Number of bedrooms and bathrooms
- Age and overall condition
- Lot size and usable outdoor space
- Renovations and upgrades
- Garage, basement, and other property features
- Recent sales and current competing listings
Example: Suppose a home in Mechanicsville is listed for $475,000, but several comparable properties have recently sold between $445,000 and $460,000.
That difference doesn't automatically mean the listing is overpriced. The home could have meaningful upgrades, a larger lot, or other features that justify a premium.
However, it does mean you should investigate the pricing before offering the full asking price or more.
These figures are hypothetical and do not represent actual Mechanicsville sales.
Understand the Difference Between Price and Value
A home can sell above its asking price without necessarily being overpriced.
For example, a seller might intentionally list below comparable market values to attract attention.
Likewise, a home can sell below asking price and still be expensive relative to comparable properties.
The more useful question is:
Does the price make sense based on the home's condition, location, comparable sales, and your financial situation?
Compare Homes Within the Same Local Market
Southern Maryland isn't one uniform housing market.
Properties in Waldorf, California, Lusby, and Leonardtown can differ significantly in location, housing characteristics, amenities, and buyer demand.
Even homes within the same county may not be directly comparable.
A knowledgeable local agent can help identify appropriate comparable properties rather than relying on broad countywide averages.
2. Set Your Maximum Budget Before Making an Offer
One of the most effective ways to avoid overpaying in a competitive housing market is to establish your financial limits before you become emotionally invested in a property.
Mortgage Preapproval Isn't the Same as Affordability
Mortgage preapproval can help you understand how much a lender may be willing to finance.
However, being approved for a certain amount doesn't mean you should necessarily spend that much.
Your actual comfort level depends on your household expenses, savings, lifestyle, and financial priorities.
For example, a buyer approved for a $500,000 purchase may decide that a $450,000 home provides a more manageable monthly payment.
That decision can create room for other priorities, including home maintenance, retirement savings, travel, or unexpected expenses.
Calculate the Total Cost of Homeownership
Your monthly mortgage payment is only part of the cost of owning a home.
Consider the following expenses:
| Expense | What to consider |
|---|---|
| Mortgage principal and interest | Monthly loan repayment |
| Property taxes | Taxes based on applicable local assessments and rates |
| Homeowners insurance | Coverage costs and deductibles |
| Mortgage insurance | May apply depending on the loan |
| HOA or condominium fees | Community or building assessments |
| Utilities | Electricity, water, heating, and other services |
| Maintenance | Repairs, servicing, and replacement costs |
| Emergency savings | Funds for unexpected expenses |
For Southern Maryland buyers, property-specific expenses may also include private well maintenance, septic system servicing, or waterfront-related insurance considerations.
Establish Your Walk-Away Number
Before submitting an offer, decide on the maximum amount you're willing and financially able to pay.
Your walk-away number should reflect:
- Comparable property values
- Your available cash
- Your estimated monthly payment
- Closing costs
- Potential repairs
- Appraisal-gap exposure
- Emergency reserves
Once you've established that number, avoid increasing it simply because another buyer is interested.
A competitive offer should still be a financially responsible offer.
3. Recognize the Warning Signs of an Overpriced Home
Not every expensive home is overpriced. Some properties legitimately command premiums because of their condition, location, or unique features.
However, certain warning signs deserve closer attention.
The Asking Price Isn't Supported by Comparable Sales
If a property's asking price is substantially higher than similar recently sold homes, ask what justifies the difference.
A newly renovated kitchen or upgraded flooring may add appeal, but those improvements don't necessarily increase market value dollar for dollar.
The Home Has Significant Deferred Maintenance
A property may look attractive during a showing while hiding expensive maintenance needs.
Potential concerns include:
- Aging roofing materials
- Outdated HVAC equipment
- Water intrusion or moisture problems
- Foundation or structural concerns
- Electrical or plumbing deficiencies
- Deteriorating exterior components
- Aging septic systems
These issues don't automatically make a home a bad purchase.
They do affect how much you should reasonably pay, particularly when repairs could require substantial additional investment.
Cosmetic Upgrades Are Driving the Price
Fresh paint, new fixtures, and attractive staging can make a property feel more valuable.
However, cosmetic improvements should be evaluated alongside the home's major systems, structural condition, and comparable sales.
Don't let beautiful presentation distract you from the property's underlying condition.
The Listing Price Relies on Unsupported Assumptions
A seller may believe their home is worth more because of personal improvements, sentimental value, or expectations about future appreciation.
Those factors don't necessarily establish market value.
A sound offer should rely on available evidence rather than assumptions about what the property might be worth someday.
4. Make a Competitive Offer Without Automatically Offering More
In a competitive housing market, price matters, but it isn't always the only factor a seller considers.
A well-structured offer may be attractive without requiring you to exceed your financial limits.
Obtain Strong Mortgage Preapproval
Before beginning your home search, speak with a qualified mortgage lender about financing options and preapproval.
A well-documented preapproval can demonstrate that you've taken meaningful steps toward obtaining financing.
However, preapproval isn't a guarantee that the loan will close. Final approval depends on underwriting, property requirements, and other conditions.
Consider the Seller's Preferred Timeline
Some sellers want to close quickly.
Others may need additional time to relocate or coordinate another purchase.
When appropriate, adjusting your proposed closing date or possession arrangements may make your offer more appealing.
These terms should still work with your lender, moving plans, and contractual obligations.
Understand Earnest Money
Earnest money is a deposit that demonstrates a buyer's commitment to the transaction.
Depending on the contract, the deposit may ultimately be credited toward the buyer's closing costs or down payment.
Offering a larger deposit may strengthen an offer, but it also increases the amount of money potentially at risk if the buyer defaults or fails to meet contractual obligations.
Review the deposit provisions and applicable contingencies before committing funds.
Evaluate Escalation Clauses Carefully
An escalation clause is a contract provision that may automatically increase your offer when a competing offer meets specified conditions.
For example, a buyer might offer $450,000 with an escalation of $2,000 above a qualifying competing offer, up to a maximum of $465,000.
While escalation clauses can be useful in certain situations, they also require careful drafting and evaluation.
Consider whether the clause:
- Has a clear maximum purchase price
- Defines the qualifying competing offer
- Requires appropriate supporting documentation
- Complies with applicable contract requirements
- Creates potential appraisal-gap exposure
Not every seller will accept an escalation clause, and not every situation calls for one.
Strengthen Terms Without Giving Up Essential Protections
An attractive offer doesn't have to involve waiving every contingency.
Buyers can sometimes improve their position through clear financing documentation, realistic deadlines, and thoughtful contract terms.
The objective is to present an offer that is both competitive and manageable.
5. Protect Yourself with Inspections and Appraisals
When multiple buyers are competing for a home, some may consider waiving inspections or appraisal contingencies.
Before making that decision, understand the financial risks.
Why Home Inspections Matter
A home inspection helps buyers better understand the property's condition.
Depending on the property and inspection scope, the process may identify issues involving:
- Roofing and exterior components
- Heating and cooling equipment
- Plumbing and electrical systems
- Moisture intrusion
- Structural concerns
- Safety-related defects
An inspection doesn't guarantee that every problem will be discovered.
However, it can provide valuable information before a buyer becomes fully committed to the purchase.
For homes with private wells, septic systems, or specialized features, additional evaluations may be appropriate.
Understand the Appraisal Process
An appraisal is a professional opinion of a property's value prepared for a specific purpose, often mortgage lending.
Lenders commonly require appraisals to help assess the collateral supporting a mortgage.
If the appraised value is lower than the contract price, the buyer may need to address the difference.
What Happens If a Home Appraises Below Your Offer?
Consider this hypothetical example:
| Illustrative appraisal gap | Amount |
|---|---|
| Contract price | $475,000 |
| Appraised value | $460,000 |
| Difference | $15,000 |
Hypothetical figures for educational purposes, not actual Southern Maryland market data.
If the appraisal comes in $15,000 below the purchase price, the lender may calculate the loan using the lower appraised value.
Depending on the loan terms and contract, possible options include negotiating a lower purchase price, contributing additional cash, challenging the appraisal through the appropriate lender process, or exercising an applicable contractual right.
An appraisal contingency may provide certain protections, but the specific language and deadlines matter.
Be Careful with Appraisal-Gap Coverage
Some buyers agree to cover a defined difference between the contract price and the appraised value.
Before offering appraisal-gap coverage, confirm how much additional cash you could need and whether that amount would reduce important savings.
For example, agreeing to cover up to $10,000 doesn't mean the appraisal will necessarily be $10,000 low.
It means you may be accepting a financial obligation up to that limit, subject to the exact contract language.
Never assume that offering above asking price guarantees the property will appraise for the purchase amount.
6. Avoid Emotional Decisions During a Bidding War
Buying a home can be exciting, especially when you find a property that seems perfect.
But excitement can turn into financial pressure when multiple buyers are interested.
Don't Treat the Purchase Like a Competition You Must Win
The goal of buying a home isn't simply to beat other buyers.
It's to purchase a property that fits your needs and financial circumstances.
Winning a bidding war at an unsustainable price may create challenges long after closing.
Separate Must-Haves from Nice-to-Haves
Before touring properties, identify your priorities.
Your must-haves might include a certain number of bedrooms, sufficient living space, or a practical commute.
Nice-to-haves could include upgraded countertops, a finished basement, or a larger outdoor entertaining area.
This distinction can help you evaluate alternatives when a particular property becomes too expensive.
Avoid Making Decisions Based on Fear
Statements such as "You'll never find another home like this" can create unnecessary urgency.
Some properties are genuinely unique, but buyers should still evaluate affordability, condition, and market evidence.
Take the time available under the circumstances to review the information that matters.
Know When to Walk Away
Walking away from a home isn't necessarily a failure.
Sometimes it's the decision that protects your ability to purchase a better-fitting property later.
If the price exceeds your established limit or the contract creates risks you're uncomfortable accepting, it may be appropriate to continue your search.
7. Consider Southern Maryland Property-Specific Costs
Southern Maryland offers a wide range of housing options, including suburban neighborhoods, rural properties, historic homes, and waterfront residences.
Each property type can involve different expenses and due-diligence considerations.
Private Wells and Septic Systems
Some homes in St. Mary's, Charles, and Calvert counties rely on private wells or septic systems instead of public utilities.
Before purchasing, consider the age, condition, maintenance history, and inspection needs of these systems.
A septic system that requires significant repair or replacement can materially affect the overall cost of ownership.
Buyers should also review applicable records and consult qualified inspectors or local authorities when appropriate.
Waterfront and Flood-Related Considerations
Waterfront homes can offer desirable views and access to the Chesapeake Bay, Patuxent River, Potomac River, and surrounding waterways.
However, buyers should evaluate additional considerations such as:
- Flood risk and insurance requirements
- Shoreline erosion
- Bulkhead or shoreline maintenance
- Drainage and storm exposure
- Applicable environmental restrictions
- Dock or pier condition and permitting
A waterfront property's purchase price is only one part of its potential long-term cost.
You can review property-specific flood information through the FEMA Flood Map Service Center.
HOA Fees and Community Restrictions
Some Southern Maryland neighborhoods have homeowners associations or condominium associations.
Review applicable fees, governing documents, restrictions, and available financial information.
A lower purchase price doesn't always mean lower overall housing expenses if recurring association fees or special assessments are substantial.
Older Homes and Maintenance Needs
Historic and older properties may have architectural character and desirable locations.
They may also require additional attention to roofing, insulation, electrical systems, plumbing, and other components.
Consider the property's age and condition when developing your offer strategy.
Commute-Related Ownership Costs
For buyers commuting to Naval Air Station Patuxent River, Joint Base Andrews, Washington, D.C., Northern Virginia, or other regional employment centers, location can influence more than convenience.
Fuel, tolls, vehicle maintenance, and time spent commuting can affect the overall financial practicality of a home.
A property with a lower asking price may not always represent the most economical option when recurring transportation expenses are considered.
8. Work with a Local Real Estate Professional
A knowledgeable real estate professional can help buyers interpret property information and develop a thoughtful offer strategy.
The goal isn't simply to submit the highest offer.
It's to understand the opportunity, evaluate the risks, and make an informed decision.
Use a Property-Specific Comparative Market Analysis
An experienced local agent can help evaluate comparable sales, active competition, and relevant property differences.
This information provides context for determining whether an asking price is reasonable.
Develop a Negotiation Strategy
Every transaction is different.
A useful negotiation strategy considers the property's market position, seller priorities, financing requirements, and the buyer's financial limits.
An agent can help explain potential advantages and disadvantages of different offer terms.
Understand Contract Deadlines and Contingencies
Real estate contracts contain important obligations and deadlines.
Missing a notice or contingency deadline can have significant consequences.
Your agent can help coordinate transaction steps and explain the practical implications of contract terms, while a qualified attorney can provide legal advice when needed.
Benefit from Southern Maryland Market Knowledge
Buyers searching across St. Mary's, Charles, and Calvert counties benefit from understanding differences among communities, property types, and local housing conditions.
At The Southside Group Real Estate, our goal is to help buyers make informed decisions with clear communication, local expertise, and guidance focused on their interests.
Explore our Southern Maryland homebuyer resources to learn more about preparing for your next purchase.
Frequently Asked Questions About Avoiding Overpaying for a Home
How do I know if I'm overpaying for a house?
Compare the proposed purchase price with recently sold similar properties, consider the home's condition and features, and evaluate whether the total ownership cost fits your budget. A comparative market analysis and professional appraisal can provide additional information, although neither guarantees future resale value.
Is it ever worth offering above the asking price?
Yes. Offering above asking price may be reasonable when comparable sales support a higher value or the property meets important buyer priorities. However, the offer should still fit your financial limits, and you should understand potential appraisal and financing risks.
What happens if a house appraises below my offer?
A low appraisal may affect the amount a lender is willing to finance. Depending on your contract and financing, you may negotiate with the seller, contribute additional cash, request an appraisal review through your lender, or use an applicable contingency. Your options depend on the specific agreement.
Should I waive a home inspection to win a bidding war?
Waiving an inspection can expose you to costly problems that may not be apparent during a showing. Before considering that approach, understand the property's condition, the contract language, and your ability to absorb unexpected repair costs. A qualified real estate professional can help you evaluate available options.
How much over asking price should I offer?
There is no universal amount or percentage that buyers should offer above asking price. The appropriate offer depends on comparable sales, property condition, market competition, financing, and your budget. In some situations, offering at or below asking price may be more appropriate.
Can I negotiate after an inspection?
Potentially. If your contract provides an inspection negotiation opportunity, you may be able to request repairs, a credit, or a price adjustment. The seller isn't necessarily required to agree, and your rights depend on the contract terms and deadlines.
Buy Smart, Not Just Fast
A competitive housing market can make buyers feel like they need to act immediately or offer more than they're comfortable spending.
But purchasing a home should be about more than winning an offer.
It's about finding a property that supports your lifestyle, fits your budget, and makes sense for your long-term plans.
By reviewing comparable sales, understanding the full cost of ownership, protecting yourself through appropriate due diligence, and setting clear financial boundaries, you can make confident decisions even when competition is strong.
The Southside Group Real Estate helps buyers navigate Southern Maryland's housing market with local knowledge, thoughtful guidance, and a commitment to putting clients' interests first.
If you're preparing to purchase a home in St. Mary's, Charles, or Calvert County, connect with our Southern Maryland homebuying team to discuss your goals and develop a strategy that works for you.
FROM OUR BLOG
Charles County Events This Weekend | November 19–22, 2026
Charles County events this weekend offer plenty of opportunities to connect with the community, enjoy local entertainment, discover holiday shopping, and explore activities throughout Southern Maryland. From November 19–22, 2026, residents and visitors can find networking gatherings, live performanc
St. Mary's County Events This Weekend | November 19–22, 2026
St. Mary's County events this weekend offer a wonderful mix of local history, live entertainment, art, outdoor adventures, vintage shopping, and community activities throughout Southern Maryland! From Thursday, November 19, through Sunday, November 22, 2026, residents and visitors can explore exciti
How Southern Maryland Sellers Can Handle Multiple Offers in 2026
Receiving multiple offers on your home can be exciting, but deciding which offer to accept is not always straightforward. For homeowners navigating Southern Maryland multiple offers in 2026, the highest purchase price may not represent the strongest overall deal. An offer with favorable financing, m